Scott Bessent just reframed the case for a December rate hike
5 min read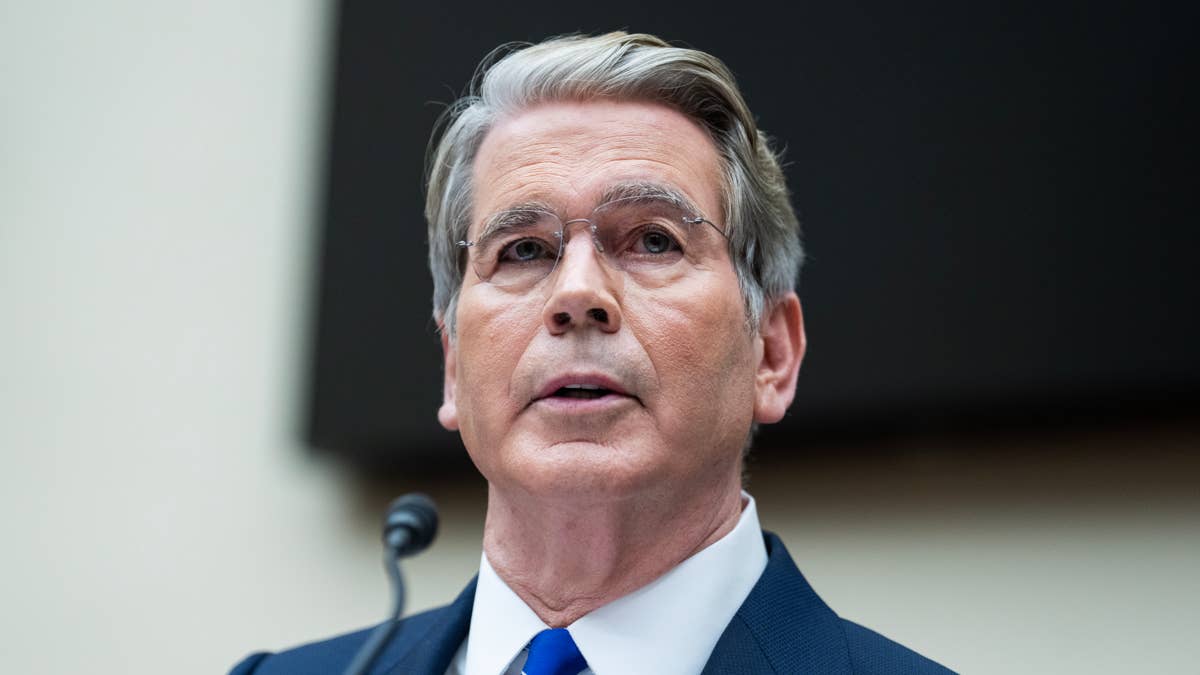
Treasury Secretary Scott Bessent said Oct. 28 that additional Federal Reserve rate hikes would not necessarily represent a policy mistake, signaling the Trump administration may tolerate further tightening if the data requires it.
Bessent’s remarks came hours after the Federal Reserve held interest rates steady at its October meeting, a widely expected decision. The pause followed a rate increase one month earlier, the first hike in three years.
Prediction markets put the odds of a December rate increase at roughly 50-50 ahead of the October decision.
Bessent’s comments mark a notable shift in tone from the administration’s typical posture on rates. President Donald Trump has repeatedly called for lower borrowing costs and previously pressured former Fed Chair Jerome Powell over monetary policy.
Bessent said he and Trump have confidence in Fed Chair Kevin Warsh, who was confirmed to the post earlier this year, and that the two believe Warsh is managing the balance between full employment and price stability well.
Bessent handed the December rate call to the Fed
Bessent did not oppose a December rate increase. Rather, he said whether one is warranted depends on what the data show between now and then, and that judgment belongs to the Fed. He said he and Trump have confidence in Warsh and are not pressing the central bank in either direction.
“I think Chair Warsh is off to a great start,” Bessent said. “As I often say, I have great confidence in him.”
Also read: Fed Chair Kevin Warsh reveals October surprise inside interest-rate pause
The Fed’s October hold left the federal funds rate unchanged after the central bank raised borrowing costs in September.
That September move was the first rate increase in three years. The Fed pointed to persistent inflation above its 2% target as the basis for tightening, and December has become the next key decision date markets are watching.
Bessent’s posture allows the Fed more operational independence than Trump-era commentary on monetary policy has typically suggested. Instead of calling for cuts, he characterized Warsh’s stewardship as strong and declined to put pressure on the central bank ahead of December’s meeting.
That restraint distinguishes his Oct. 28 comments from how the administration has talked about the Fed in the past.
The Iran war shock keeping prices above target
Bessent identified the energy-price shock tied to the U.S. conflict with Iran as the main force keeping inflation above the Fed’s 2% target. He asked the central bank to keep an open mind about whether the shock is transitory before deciding how aggressively to respond.
Monetary tightening works through demand. It raises borrowing costs, slows spending, and cools price growth that way. It does not replenish oil fields or reopen supply chains.
If the Iran conflict pushed energy prices up and those costs ease on their own, a rate hike in December addresses the wrong problem. It slows the economy without doing anything about the source of the inflation.
Bessent said he was not forecasting which outcome was more likely. He said the Fed has time to assess it before December. Getting that call wrong carries costs: tightening into a supply-driven price spike means slowing an economy that the energy shock is already straining.
On the Iran front, Bessent described Operation Economic Outcast, the Treasury-led campaign to isolate Iran’s economy, as producing results. Internal estimates, he said, put Iran’s potential economic contraction at 20% to 25%. He said the operation has been “very successful.”
Bessent said he expected the third-quarter GDP report, due Oct. 29, to show strong growth, though he added he had not yet seen the data.
Alex Wong / Getty Images
Musk’s neocloud warning didn’t spook Bessent
Bessent also addressed growing concerns about debt financing among neocloud companies, a group of specialized AI infrastructure providers that have faced market pressure in recent weeks.
Musk’s warning that more than 200 neocloud firms could face what he called “guppy-level death and consolidation” weighed on the sector. Bessent said Treasury is monitoring the space but does not view the credit stress as a systemic risk.
“I don’t think it’s problematic at all,” Bessent said. “The neoclouds are a small component of the overall ecosystem, and we’re still seeing the financing getting done. We’re still seeing the deals get done.”
More Federal Reserve:
J.P. Morgan sees Fed rate hikes going out with a bang this year
October Fed rate hike hinges on two looming economic reports
Scott Bessent sends signal on Kevin Warsh Fed rate hike
The Treasury’s assessment tracks with how regulators typically treat a niche sector under strain. Individual companies may fail or consolidate without that stress transmitting to the broader financial system.
Bessent’s comments suggest Treasury is watching for contagion but sees no reason to intervene. Whether that view holds depends on how quickly credit conditions tighten for the firms still actively financing AI infrastructure buildouts.
What the Oct. 29 GDP print could change for December
Bessent said he expected the third-quarter GDP report, due Oct. 29, to show strong growth, though he added he had not yet seen the data. The report will offer the clearest read yet on how the economy held up through a period of rising rates and energy-driven inflation.
A strong number alongside elevated inflation narrows the Fed’s case for holding. The central bank does not need to protect a fragile economy if the data show growth holding up.
A soft print changes that. It puts tightening into a slowing economy at a moment when energy costs are already eating into household and business budgets.
For bond markets, the combination of a strong GDP print and persistent inflation is the scenario most likely to extend the selloff in longer-dated Treasuries.
Mortgage rates, which track the 10-year yield, would follow. Growth stocks and high-debt companies, which are more sensitive to rate expectations, would also face pressure if December’s hike becomes the consensus view.
Bessent’s Oct. 28 comments, taken together, outlined an administration that sees the economy as durable, the Fed as capable and the path to December as data-dependent.
Whether that confidence is tested will depend on what the Oct. 29 GDP figure shows and what the next inflation reading says about how far energy prices have spread into the broader price level.
Related: Scott Bessent just opened the door to a major gold comeback
#Scott #Bessent #reframed #case #December #rate #hike