Zillow launches down payment assistance for FHA loans
4 min read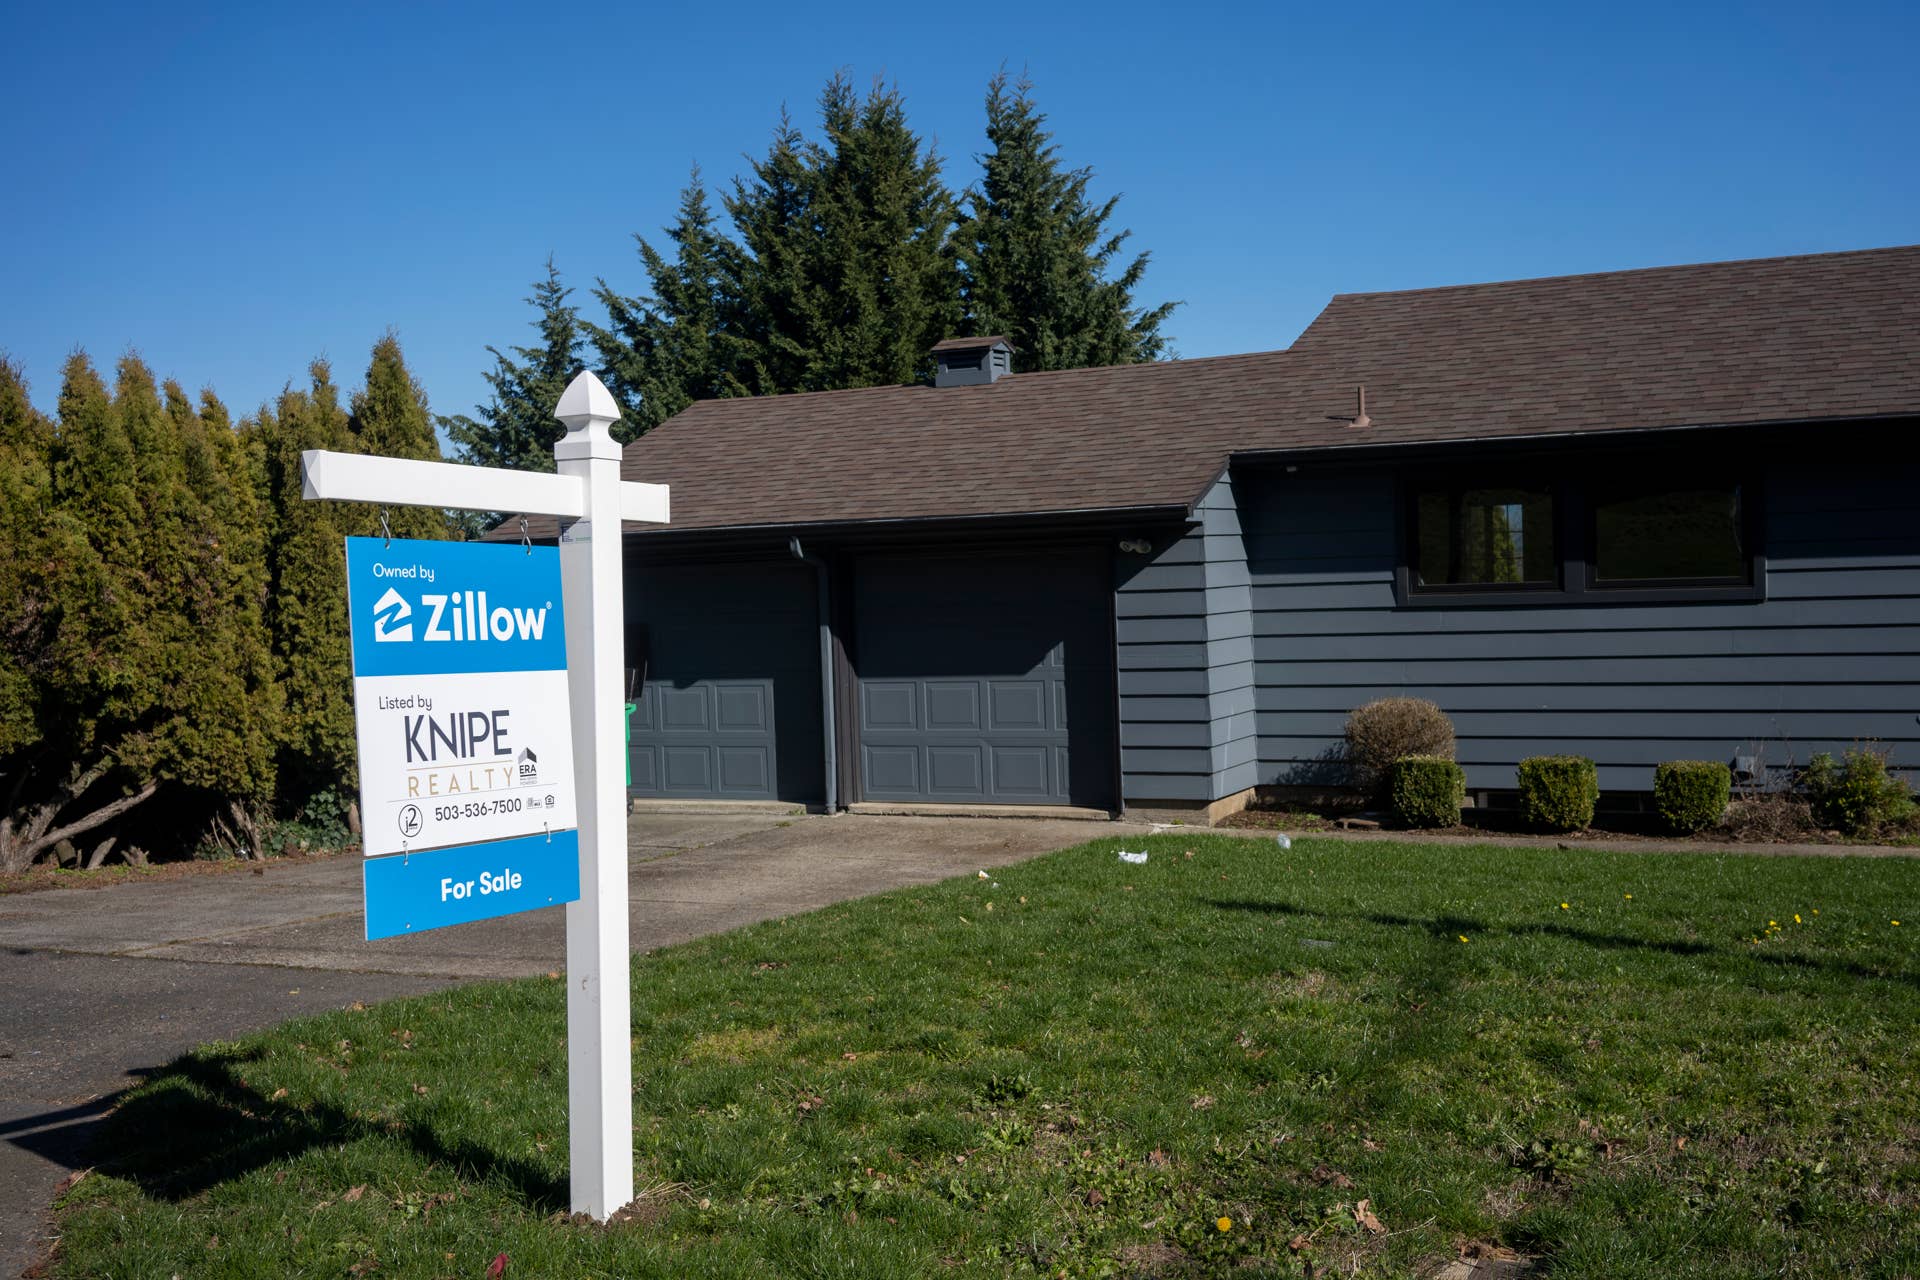
FHA loans, mortgages insured by the Federal Housing Administration, have long helped buyers afford a home. FHA loans often come with competitive mortgage rates, and borrowers can qualify with a down payment as low as 3.5%.
Still, with today’s high home prices, even a 3.5% down payment can be difficult to scrounge up. That’s why Zillow Home Loans, Zillow’s lending subsidiary, is stepping in to help.
“Buyers tell us the down payment is what’s holding them back, and we hear the same thing from agents about their clients,” said Eric Wilson, Zillow’s senior vice president and general manager of mortgages.
Zillow Home Loans launched a new down payment assistance (DPA) program on Wednesday, Oct. 28, specifically for FHA loans.
“This program helps us serve more qualified buyers by giving them a simple way to clear that hurdle, with their mortgage and down payment assistance handled in one place,” Wilson said.
So if you qualify for an FHA loan through Zillow, the company could cover your entire 3.5% down payment.
How Zillow’s assistance could help buyers reach 10% down
Although Zillow’s program can cover the minimum 3.5% down payment, the company also highlights how its assistance could help borrowers reach 10% down. Zillow emphasizes that larger down payment can mean significant long-term savings.
A median-income household in the U.S. would need 4.2 years to save for a 10% down payment on a typical home, according to Zillow research.
Read more: Mortgage payments are becoming a bigger threat to family income
But if Zillow provided 3.5%, the homebuyer would need only the remaining 6.5%, reducing the estimated time needed to save to 2.7 years. That’s a 1.5-year decrease. This assistance would also save typical households $1,080 per year in monthly housing costs.
The timing and savings would be even more notable for people who live in higher-cost areas. For example, the typical time to save for 10% down would fall from 9.1 years to 5.9 years, and annual savings would be $2,880.
More up-front equity and a lower monthly payment are two exciting opportunities for homebuyers using Zillow’s DPA program. But with FHA loans, there’s another perk many people overlook.
Why 10% down could mean lower FHA mortgage insurance costs
You may have heard of private mortgage insurance (PMI). People often mention it when discussing conventional loan costs. It’s a monthly expense homebuyers pay when their down payment is less than 20%.
The good news is that they can ask their lender to cancel PMI once they reach 20% equity, and the lender is required to cancel it once they reach 22%.
One major downside to FHA loans is that, unlike conventional loan PMI, FHA mortgage insurance generally can’t be canceled just because you’ve built up enough equity.
However, there’s an important exception. If you make a down payment of at least 10%, you can generally stop paying FHA mortgage insurance after 11 years, according to the U.S. Department of Housing and Urban Development.
More Mortgages and Housing:
Mortgage rates could still rise even after Fed holds rates steady
Zillow warns Americans on housing market, mortgage rates
Kevin O’Leary sends a strong warning to all first-time home-buying Americans
You’ll pay 1.75% of your loan amount for FHA mortgage insurance at closing. You’ll also make monthly payments. The monthly amount varies based on several factors, but it typically comes to 0.15% to 0.75% of your principal balance, according to HUD.
Getting to 10% down doesn’t just give you more equity or reduce the amount you need to borrow. It could also help you eliminate FHA mortgage insurance after 11 years, potentially saving you thousands over the life of your loan.
How Zillow’s down payment assistance program works
So, we’ve established how useful DPA programs can be for FHA loans, especially if they help you reach a 10% down payment. Now, let’s dive into how the Zillow Home Loans DPA program works:
Amount: Zillow loans you up to 3.5% of the purchase price or the appraised value, whichever is lower.
Structure: Zillow extends a second loan with no interest and no monthly payment.
Forgiveness: Zillow forgives the second loan after five years if you live in the home (don’t rent it out) and make on-time payments.
Repayment: If you sell, move out, or refinance before the five-year mark, you have to repay the second loan in full.
Essentially, Zillow’s assistance functions as an interest-free second loan that doesn’t require monthly payments. If you meet the program’s occupancy and payment requirements for five years, Zillow forgives the loan, meaning you won’t have to repay the assistance.
Zillow offers down payment assistance in the form of a no-interest, forgivable second loan.
SOPA Images / Getty Images
Who qualifies for Zillow’s down payment assistance?
Although the program could help many FHA borrowers, it has some important eligibility requirements.
First, the program is only available in 43 U.S. states and Washington, D.C. You can’t apply if you live in Arizona, Delaware, Florida, Massachusetts, New York, Vermont, or Virginia.
Borrowers must have a 640 credit score or higher. This is definitely worth noting, considering the Federal Housing Administration’s minimum credit score for FHA loans is 580 in most circumstances.
You still need to qualify for an FHA loan, which means Zillow Home Loans must determine via manual underwriting that you can afford the monthly housing payments.
“For buyers who can afford the monthly payment, we can now cover the full minimum down payment,” Wilson said.
Related: The bond market just sent home buyers an unexpected signal
#Zillow #launches #payment #assistance #FHA #loans