Divorce attorney exposes financial risks that follow separation
4 min read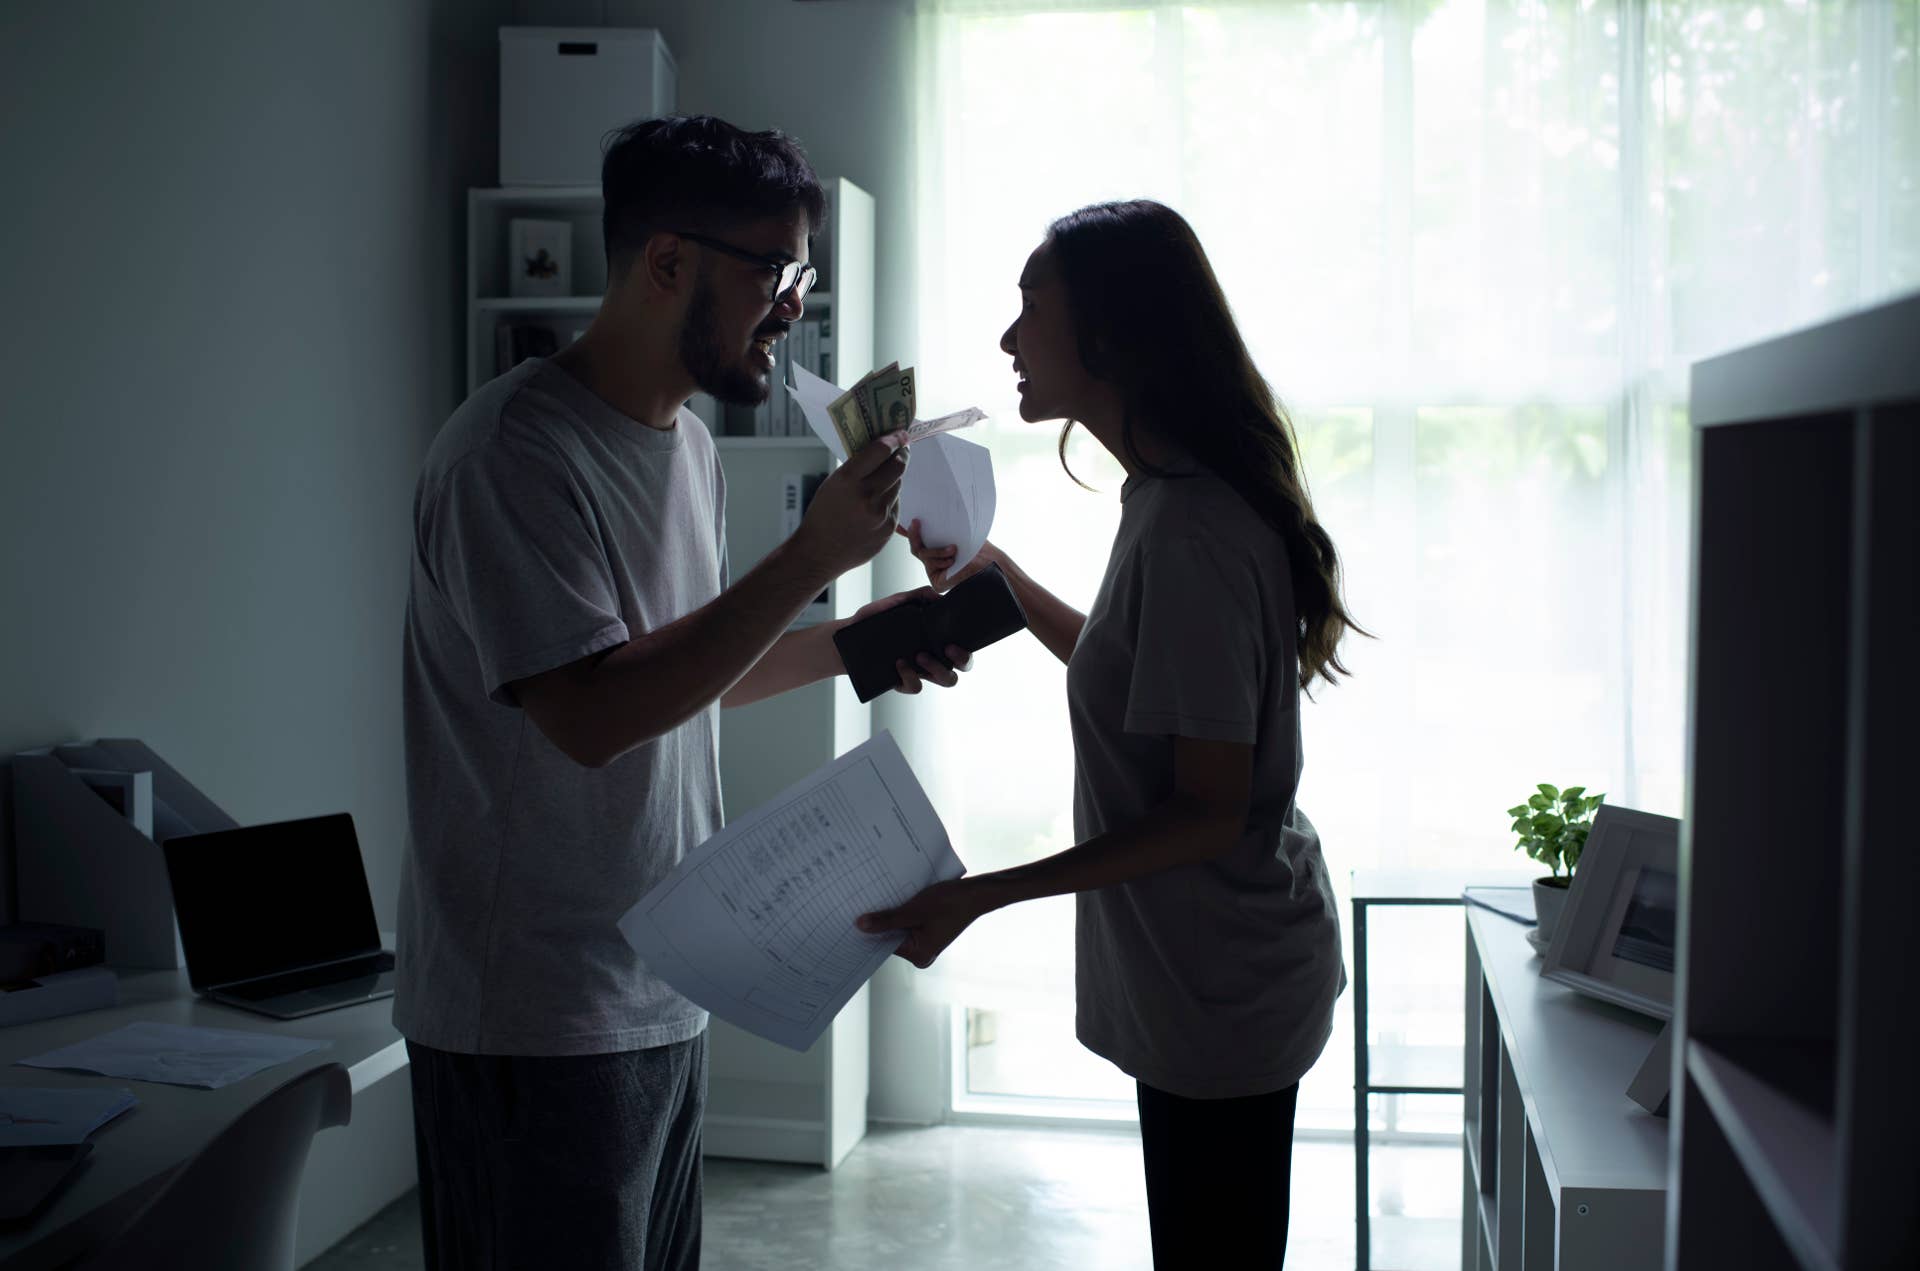
Divorce may end a marriage, but it does not always sever the financial ties between former spouses. Even after assets are divided and a decree finalized, one person may remain liable for a mortgage, credit card debt, or auto loan for years.
This is because divorce agreements do not override contracts with creditors, leaving former spouses exposed to financial obligations they may assume are settled, according to the University of Minnesota Extension.
Damian Turco, Founder and Managing Partner of Turco Legal, is licensed in Massachusetts and Florida and has handled hundreds of family law cases.
In an interview with TheStreet, he explained the financial traps separating couples often overlook, including lingering joint debts and complex compensation arrangements.
Also Read: Unhappy couples are staying married longer because divorce is a luxury
Joint debts can follow both spouses long after a settlement
The most pressing risk Turco identified involves joint debts, particularly mortgages, credit cards, and auto loans, in which both spouses signed the original agreement.
A family court can assign payment responsibility to one former partner, but that ruling has no authority over the lender holding the original contract.
Divorce attorney Damian Turco warned in an interview with TheStreet that divorce does not automatically erase joint debt obligations.
<strong>A divorce court can allocate responsibility for a debt between spouses, but that generally does not rewrite the contract they previously signed with a bank or other creditor,</strong><br>
When the assigned spouse misses a payment on a joint debt, the creditor can still pursue the other borrower for the full balance.
The divorce agreement provides no protection from the original lender, the University of Minnesota Extension confirmed.
Turco recommended refinancing mortgages into one spouse’s name, paying off shared credit card balances, and closing joint accounts before the decree is finalized.
Turco said the goal should be to sever every financial connection between former spouses rather than leave shared liabilities for creditors to collect.
Unreported income and hidden accounts undermine fair settlements
Research shows financial deception between spouses is more common than most people assume, and it undermines a court’s ability to divide property equitably.
A 2021 National Endowment for Financial Education poll found that 43% of Americans who had ever combined finances with a partner admitted to at least one act of financial deception.
More Personal Finance:
Pay raises trail inflation so Ramit Sethi says, “Ask for $5,000”
Your home insurance deductible could be $20,000. Would you be ready?
Why your next car purchase will be an affordability nightmare
Turco cautioned in the interview that suspicion alone never constitutes proof, which is why the discovery process becomes essential in these cases. Attorneys can compel sworn answers to written questions, take depositions under oath, and issue subpoenas to employers and financial institutions, he explained.
When standard discovery falls short, forensic accountants can trace money across multiple accounts, analyze tax returns and bank records together, and flag discrepancies.
Cryptocurrency holdings, closely held businesses, and multi-entity compensation packages often require this deeper forensic analysis beyond routine disclosure, Turco told TheStreet.
Courts can reopen divorce judgments when hidden assets surface and may redistribute property to favor the honest spouse, the California Courts’ Families Change guide notes.
Financial deception can distort divorce settlements, making forensic accounting, legal discovery, and full financial disclosure essential to fair property division.
Zinkevych / Getty Images
Stock options, RSUs, and private businesses carry hidden division risks
Assets like stock options, restricted stock units (RSUs), deferred compensation, and bonuses are common in divorce cases and raise two distinct legal questions. The first is what portion falls under state property division rules, and the second is what the interest is worth in practice, Turco explained.
Business valuation is nuanced in divorce because an appraisal created to raise capital uses different assumptions than one prepared for property division, he said.
Splitting every asset evenly does not always serve either party, and forced division can destroy the value it was meant to preserve, Turco noted. Giving both spouses ownership in a business that only one operates can create operational problems and may harm both parties financially.
Kara Duckworth, a Partner of Regis Group at Mercer Advisors, warned in a Kiplinger column about overlooked dangers in the division of assets. Two retirement accounts with identical statement balances can deliver very different income depending on whether they are pre-tax or Roth, Duckworth wrote.
Access to shared records can disappear quickly after a filing
Turco urged anyone considering or facing a divorce to begin organizing financial records as early as possible, ideally before a formal filing occurs. Access to joint accounts and shared statements can change rapidly once a spouse suspects that a filing is imminent, Turco warned.
The essential records include several years of personal and business tax returns, which can reveal income patterns and undisclosed accounts.
Bank, brokerage, retirement, and investment statements from every account either spouse can lawfully access round out the core list, Charles Schwab’s divorce preparation guide advised.
Turco recommended downloading copies of every statement you are legally entitled to access and saving them in a secure digital location before the proceedings begin.
For spouses with business-owning partners, the needed records also include business financial statements, employment agreements, and RSU documentation, he noted.
Protecting your finances means acting before the final decree
Financial disclosure can involve thousands of pages, and when records arrive sorted and labeled, attorney time shifts from paperwork to strategy, meaningfully reducing legal fees, Turco said.
Engaging a financial adviser before a settlement is finalized can reveal blind spots that surface only after asset division concludes, Duckworth wrote.
Early preparation and professional guidance remain the most protective steps a separating spouse can take through the settlement process, Turco noted.
Related: Divorce Under Pressure: Budget, Cash Needs, and Retirement Planning
#Divorce #attorney #exposes #financial #risks #follow #separation